Weekly Market Intelligence: Week of September 28, 2026
The diesel run broke while the freight tape had not yet caught up: all-in rates rose in every mode on a fuel number that had already reversed, and linehaul was flat or down. An 11-page market intelligence package.
By Michael Cafarelli
Download the report (PDF, 11 pages)
EIA's diesel survey for the week ending 9/28 printed $6.382 per gallon, down 14.7 cents and the first decline since 8/31. But DAT's print still carried the record 9/21 diesel number in its fuel component, so all-in rates rose while the part you actually negotiate, linehaul, was flat or negative in every mode.
- $6.382U.S. diesel, $/gal (EIA, week ending 9/28; down 14.7¢)
- $3.63Reefer all-in $/mi (linehaul $2.71, down 2¢)
- $3.01Dry van all-in $/mi (linehaul $2.17, unchanged)
- $3.60Flatbed all-in $/mi (linehaul $2.59, down 1¢)
Three takeaways
- Your fuel table now over-recovers. The illustrative truckload surcharge fell from 54.3 to 52.0 cents per mile. A table still set to the 9/21 record over-charges 2.3 cents per mile, and a monthly reset at the September peak over-charges all of October.
- Do not renew off the 9/26 all-in. All three modes' all-in rates rose 4 to 5 cents on a fuel number that reversed two days later. Split the quote before you sign.
- Tightness is easing, not gone. National tender rejections eased to 12.54% from a summer peak near 18%, but remain well above 2024 and 2025. The leverage window is opening for shippers on truckload and closing on LTL, where Old Dominion's 4.9% GRI goes live October 5.
Inside the 11-page package
Executive summary · Reefer · LTL · Dry van · Flatbed · EDI tender decline report · Fuel surcharge report, all modes · Diesel cost by PADD (regional) · Reefer rate and reefer ROTRI 13-week comparisons.
Data sources include DAT Freight & Analytics, U.S. EIA, and the Cass Freight Index; full citations are in the PDF. The EDI tender decline section is illustrative, and some historical comparisons are analyst estimates, labeled as such in the report.
Want this analysis applied to your lanes and contracts? Get in touch.
More from the blog
Secrets: Ways to Use Today's AI
A 15-second look at RicavaIQ's Secrets: Ways to Use Today's AI, a cross-platform prompt manual with 850 deployable prompts across 17 disciplines and five AI platforms.
Watch
Weekly Market Intelligence: Week of October 5, 2026
Linehaul rose in all three truckload modes for the first time since early September while diesel fell a second straight week. An 11-page market intelligence package on reefer, LTL, dry van, flatbed, tender declines, fuel surcharges, and regional diesel.
View & download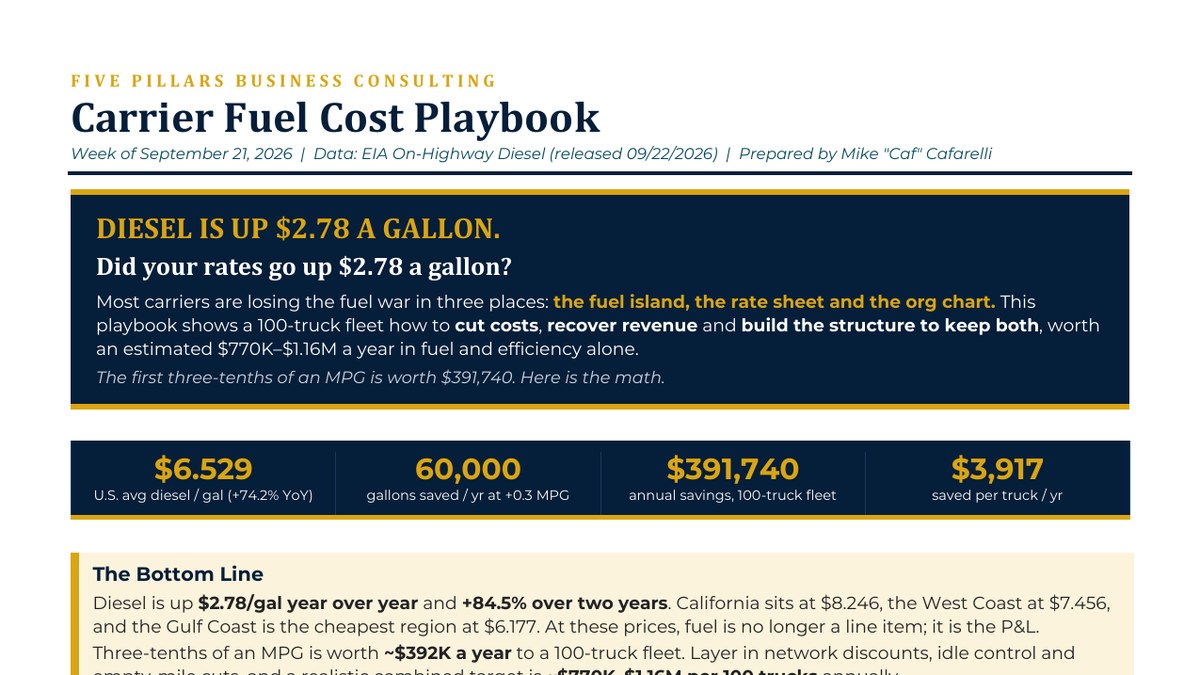
Carrier Fuel Cost Playbook
Diesel is up $2.78 a gallon. A playbook showing a 100-truck fleet how to cut fuel costs, recover revenue through fuel surcharges, and build the structure to keep both, worth an estimated $770K to $1.16M a year in fuel and efficiency alone.
View & download